Taxes down to the lot
FinZot knows what you paid for every share, so every sale is taxed on the real gain and every dividend in the year it lands.
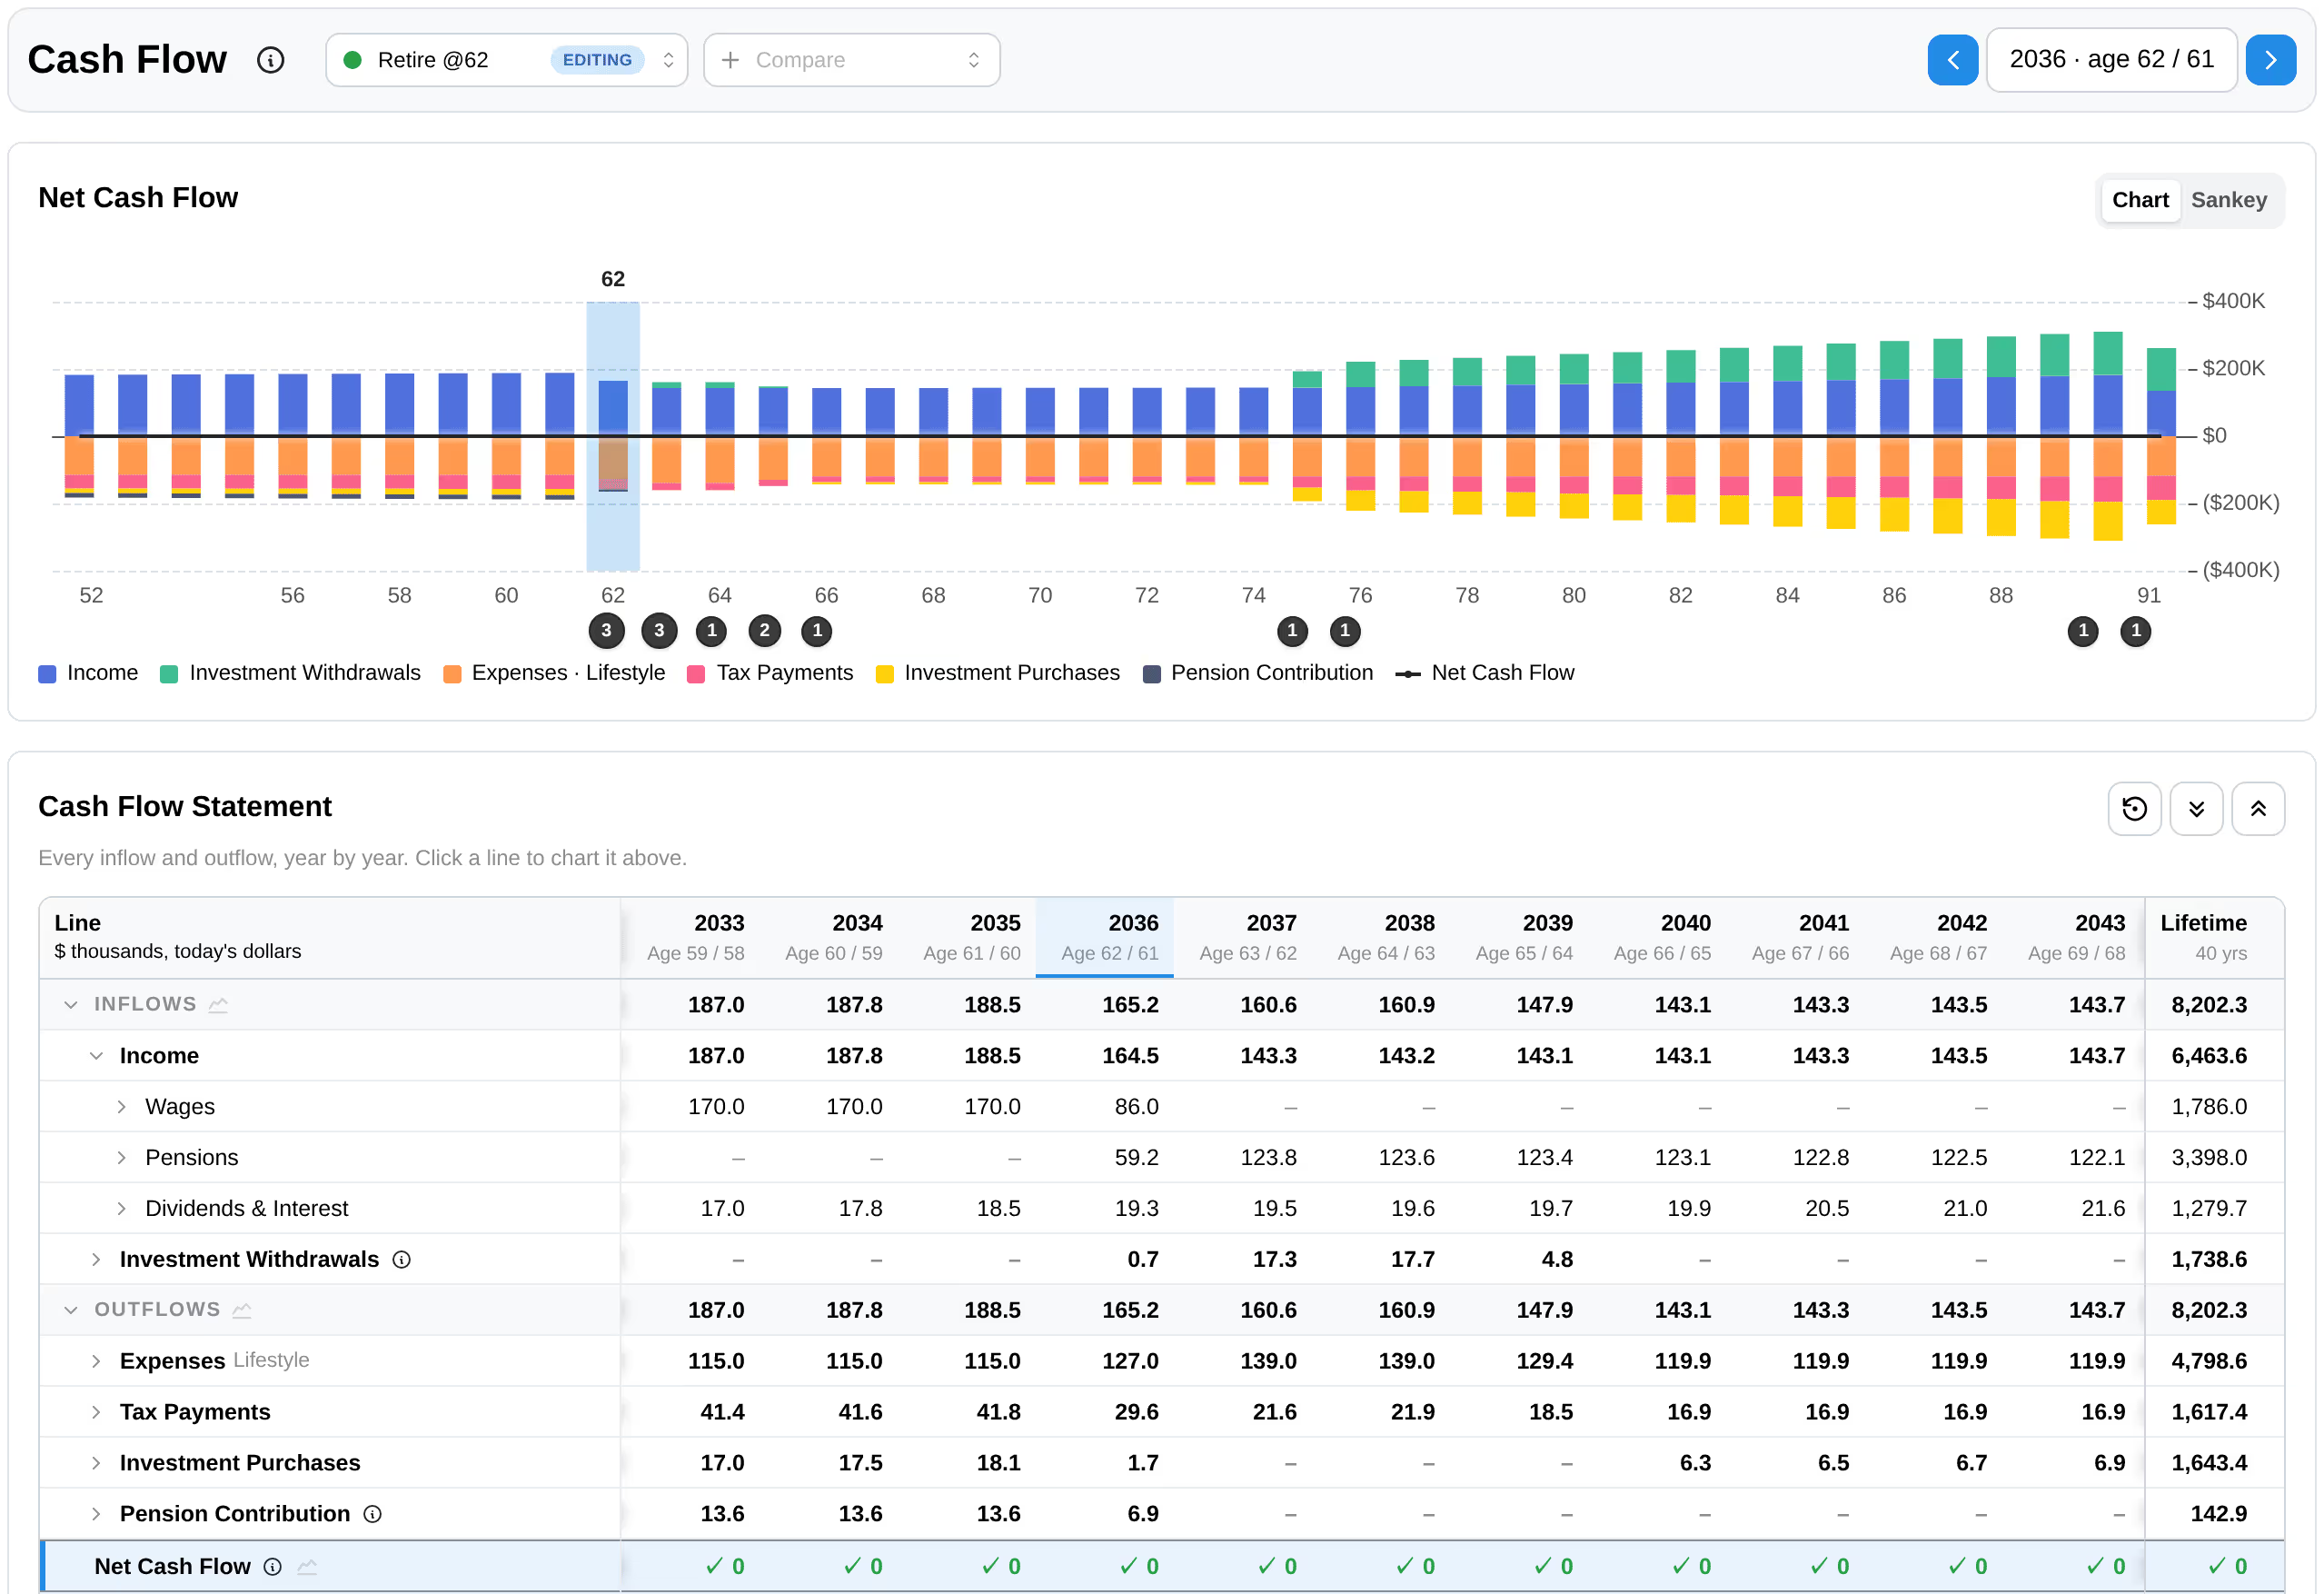
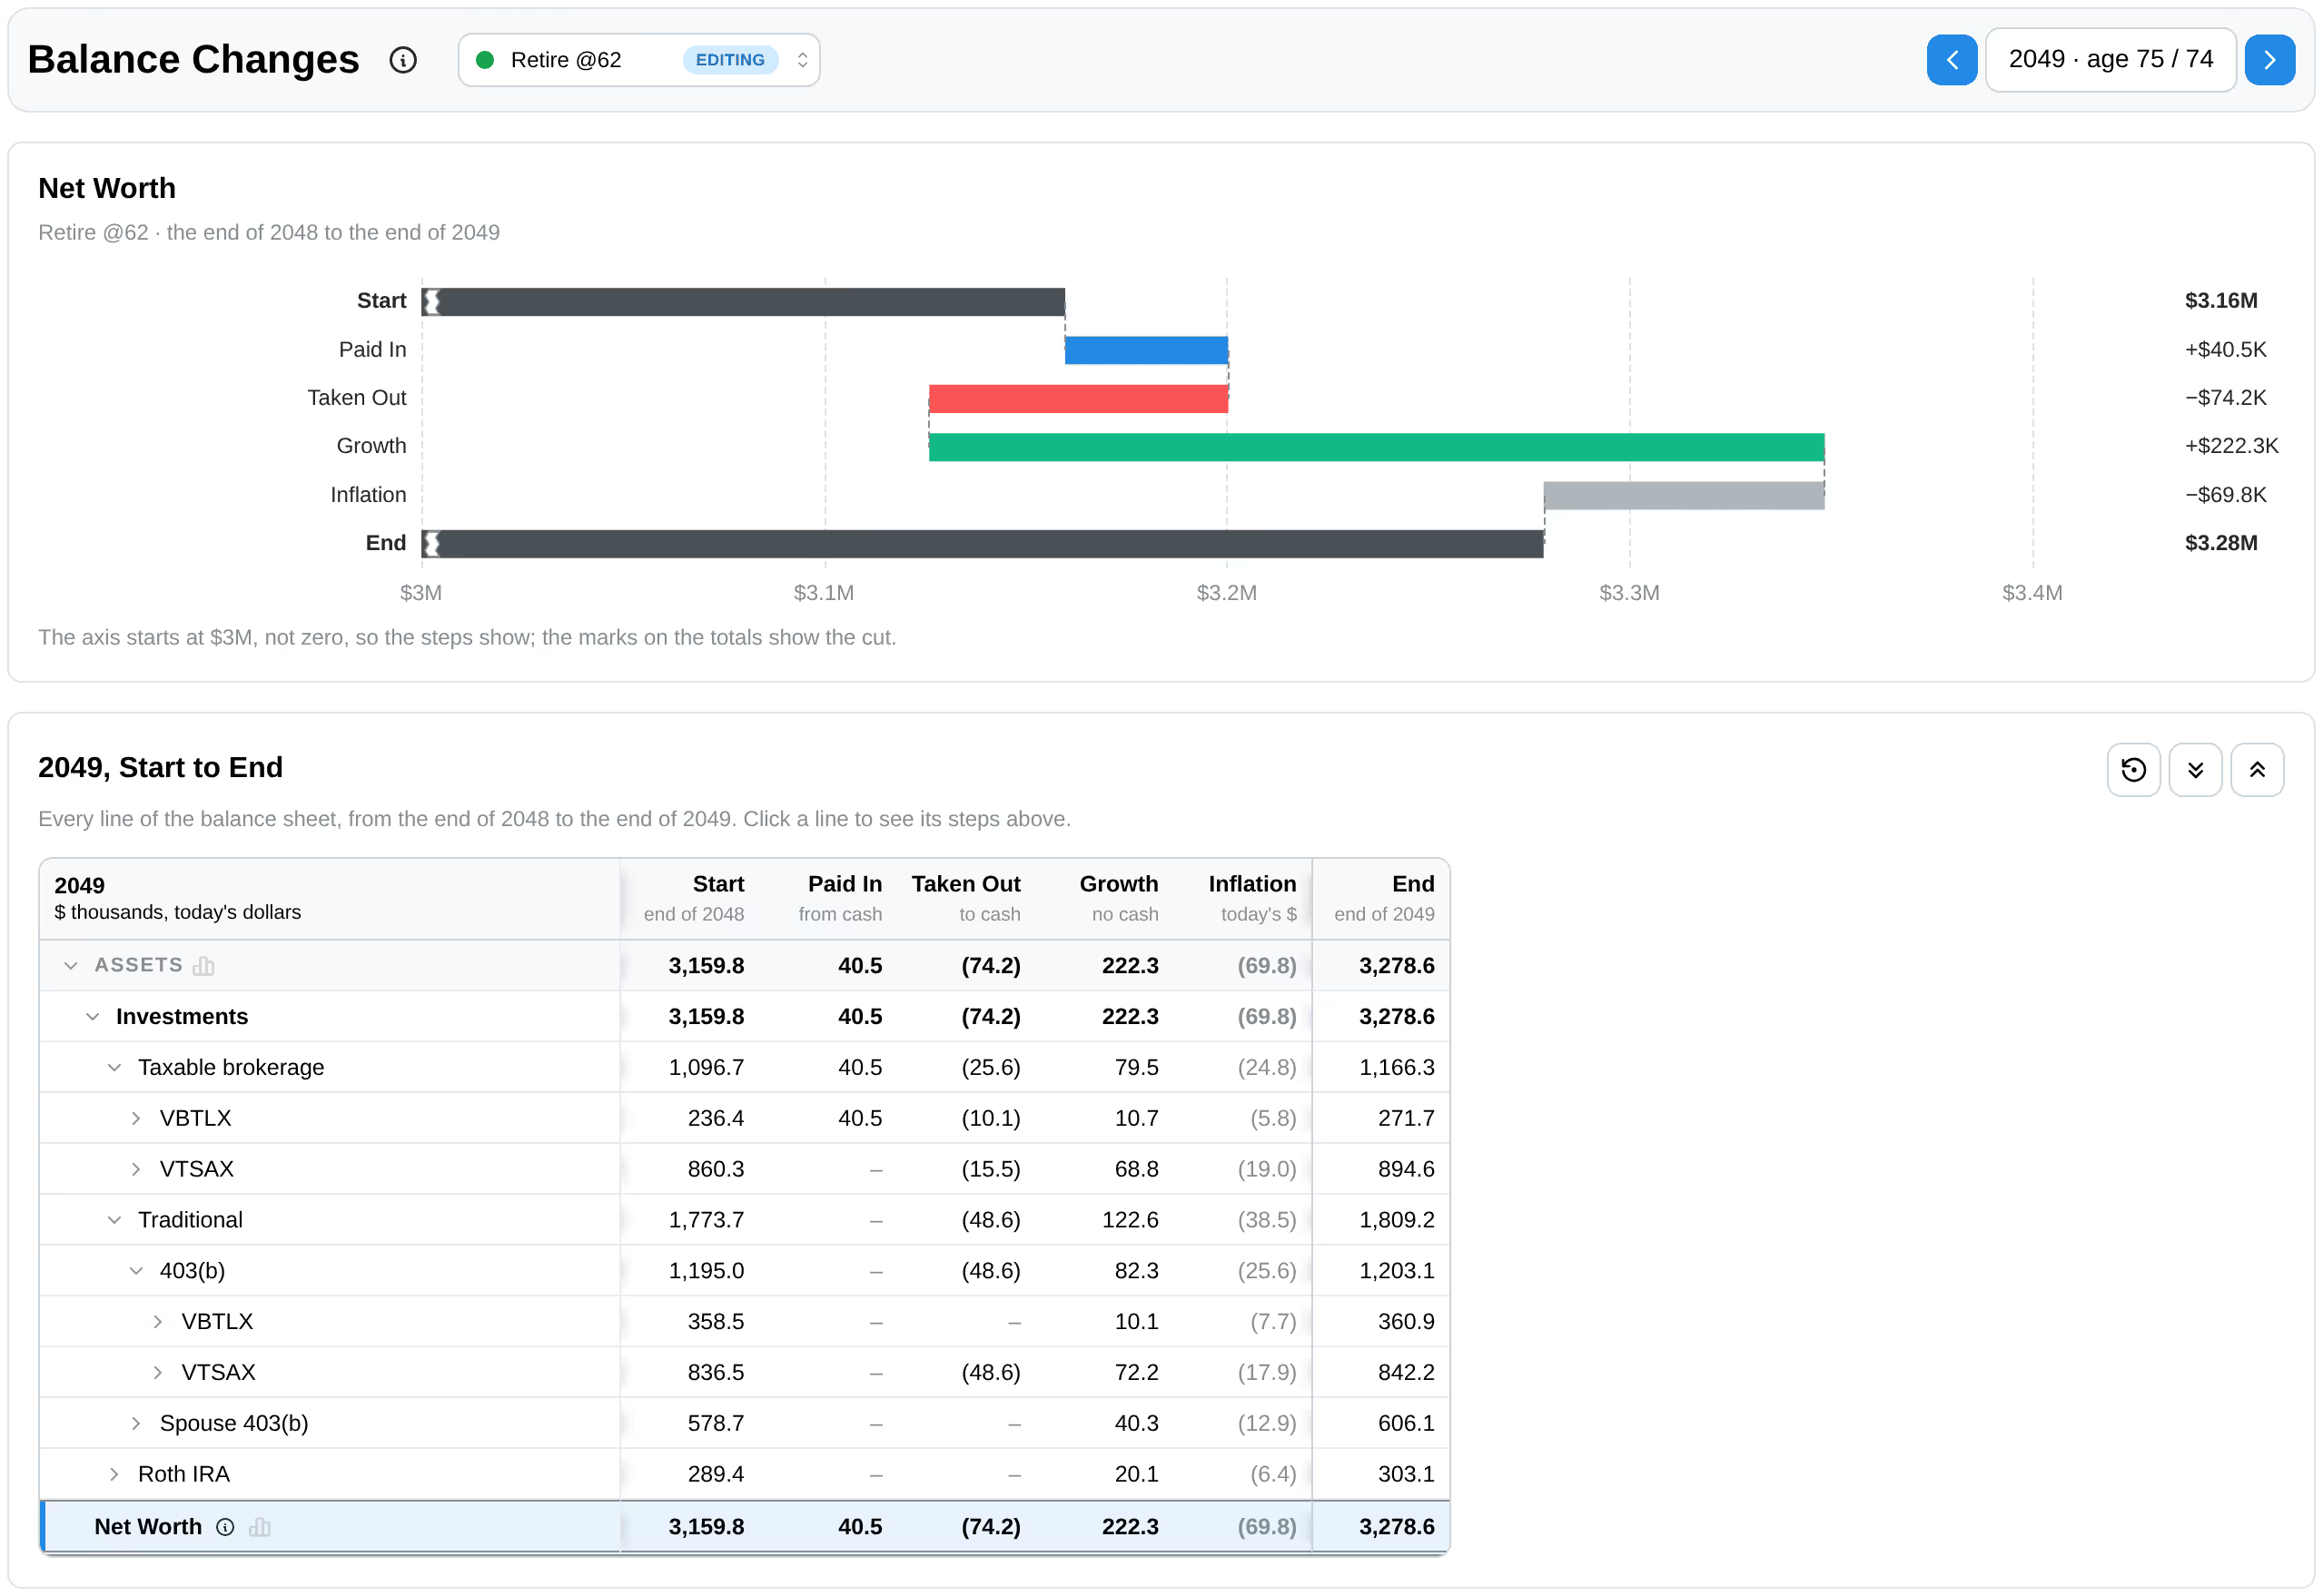
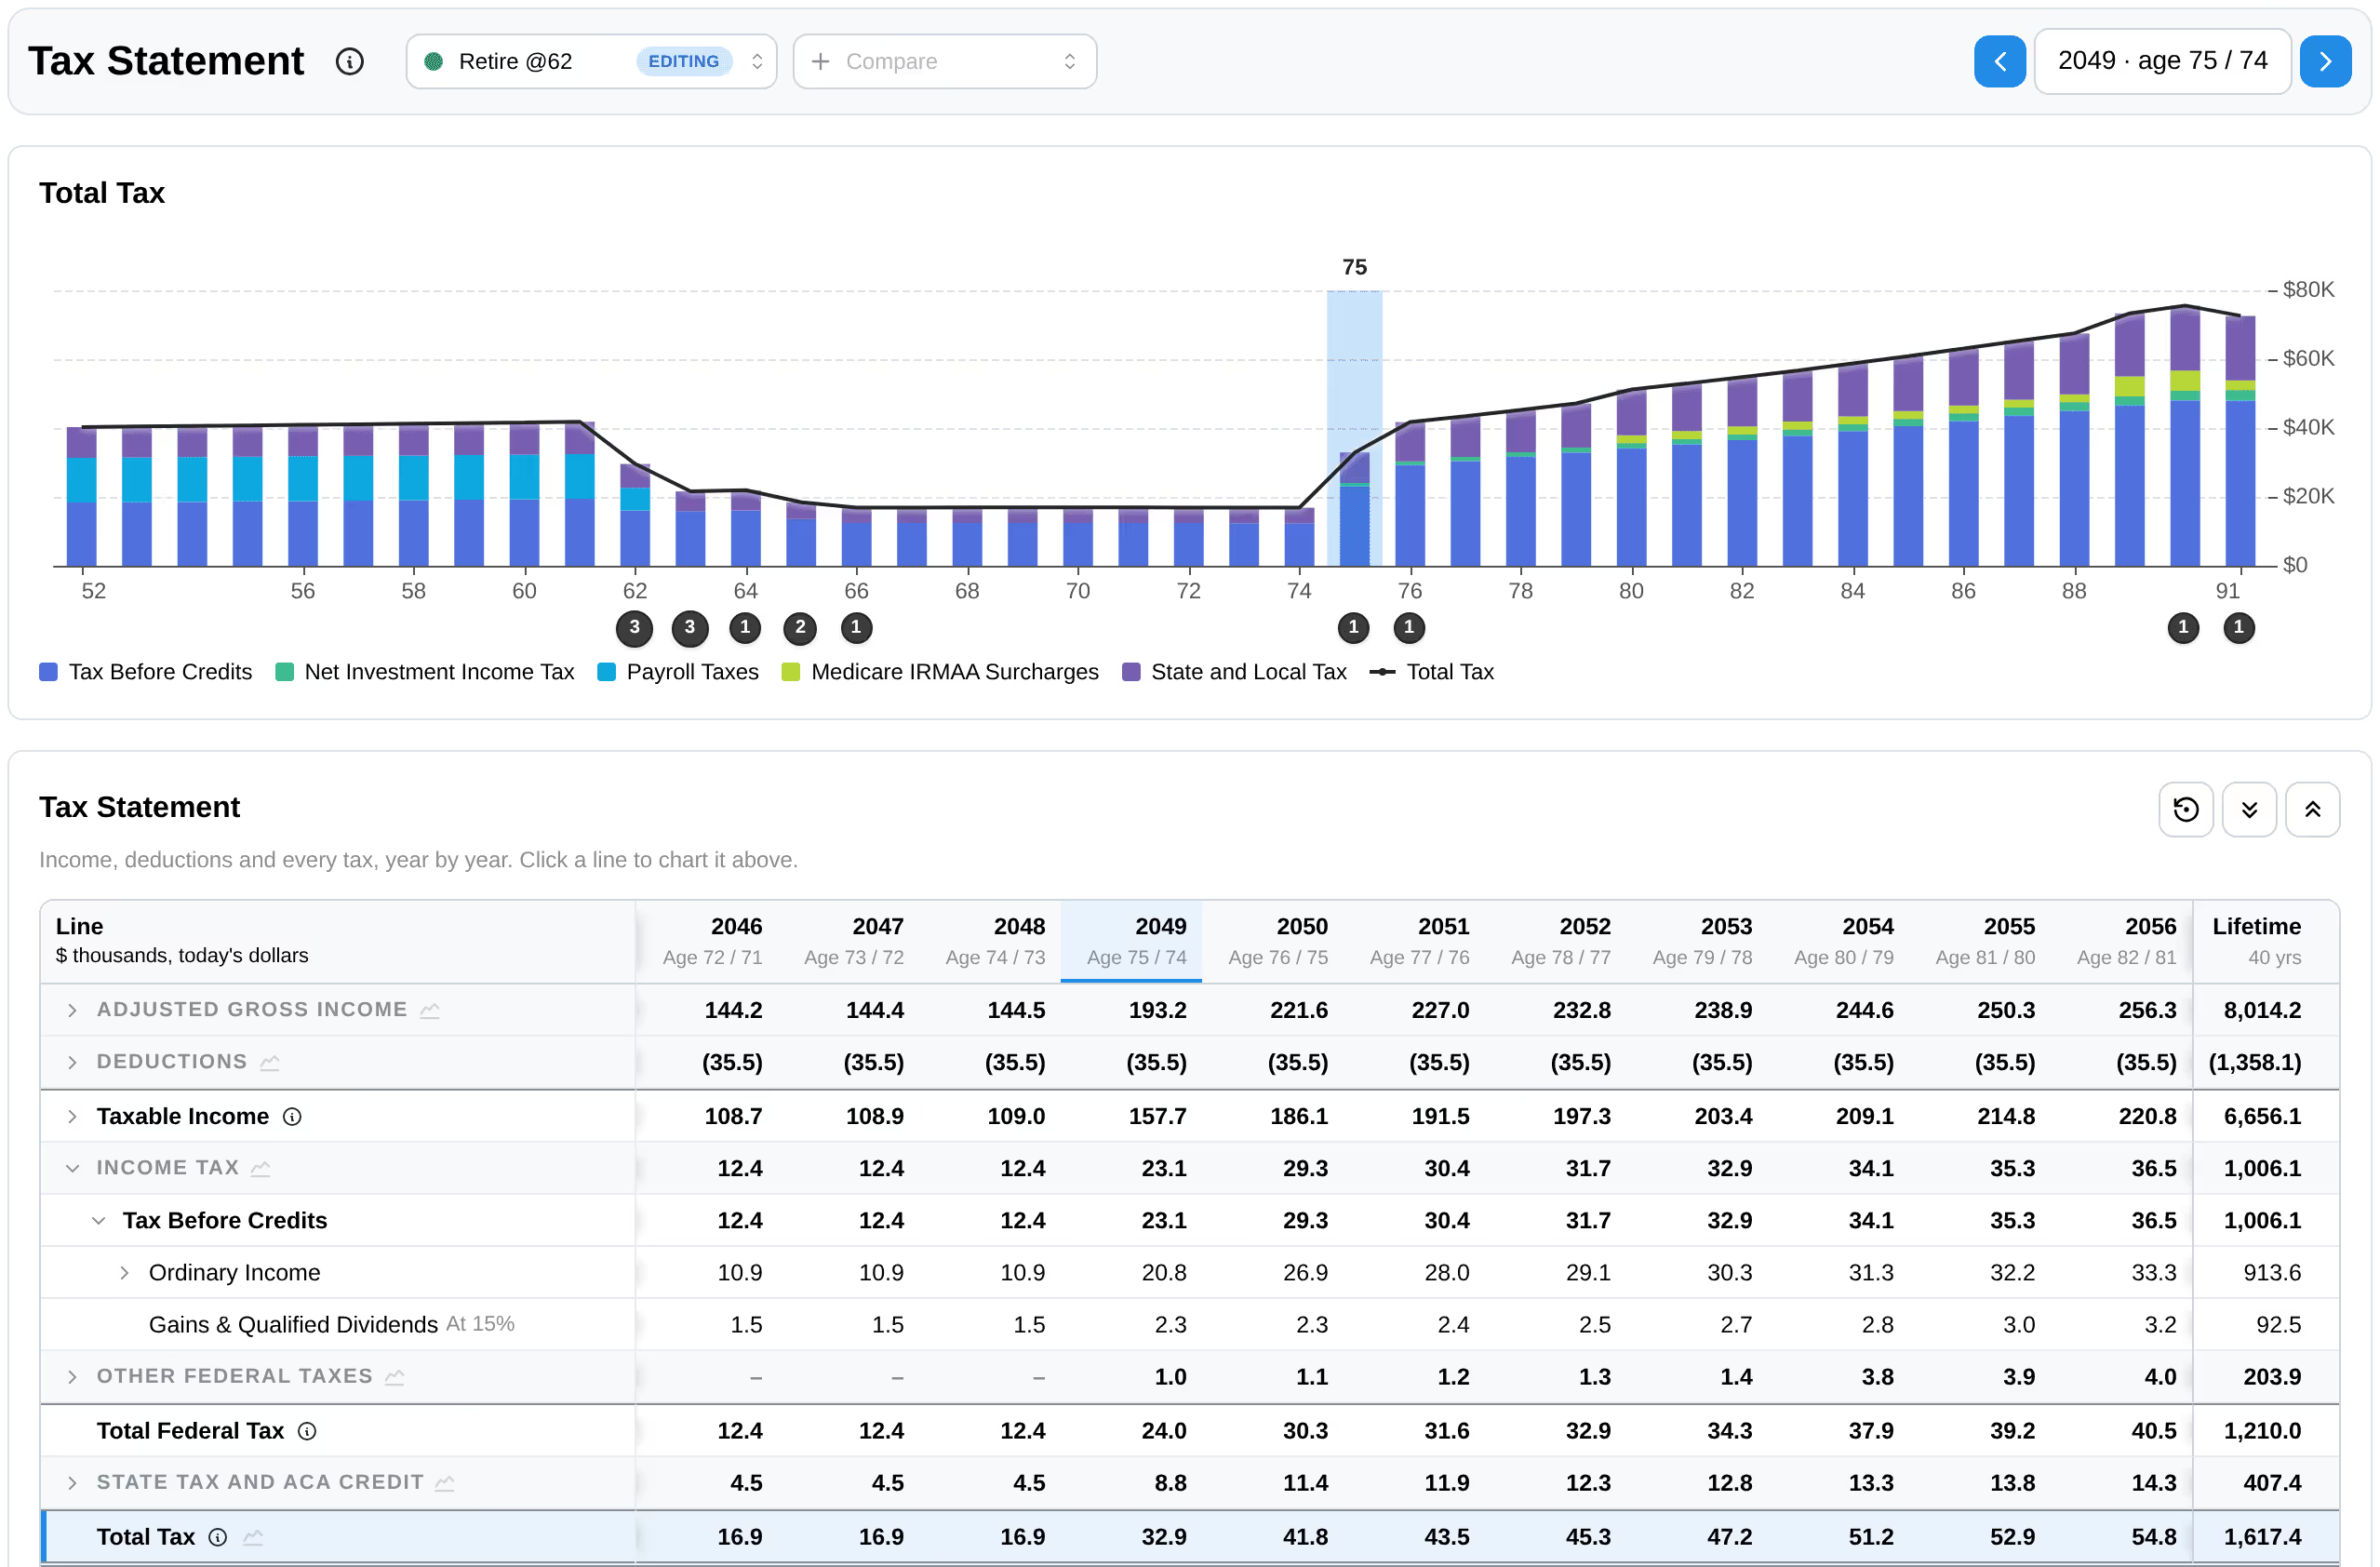
How selling is taxedCash flow, balance changes and taxes as statements, a column for every year and every line opening to its parts. Click a line to chart it across the plan.
FinZot knows what you paid for every share, so every sale is taxed on the real gain and every dividend in the year it lands.
How selling is taxedHold a muni bond fund and its interest stays out of your federal taxes but still counts toward Medicare premiums and ACA credits, just like it does in real life.
How funds are taxedA thousand trials stitched from real stretches of market history, so stocks, bonds, and inflation move together the way they actually did. Each fund is then scaled to your own expected return and volatility.
How the trials are builtFill a tax bracket, an IRMAA tier, or an ACA threshold and FinZot reruns your whole tax return until the conversion lands right on it.
How conversions are sized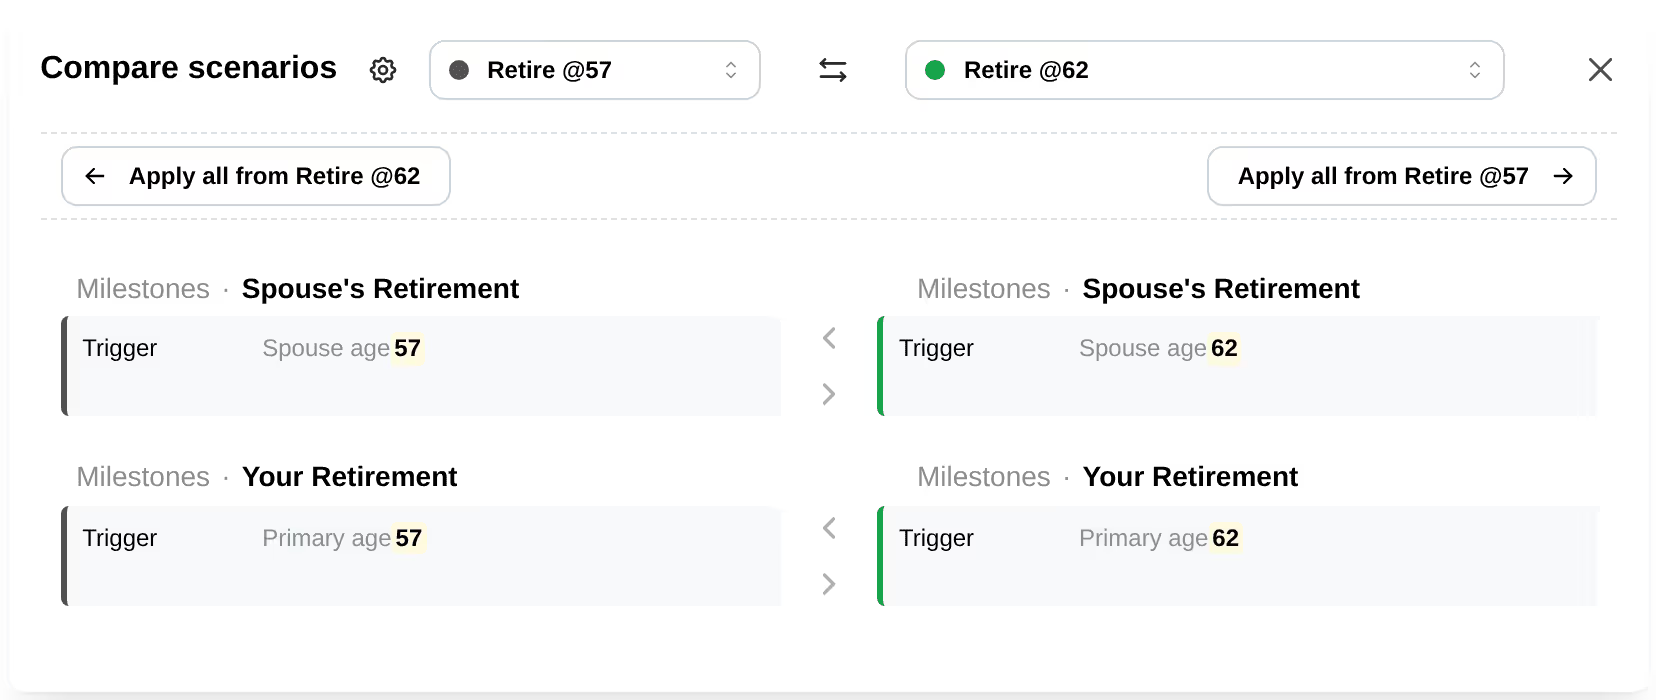
Put two scenarios side by side and every setting that differs is highlighted, down to the field. Copy one change across with a click, or apply everything from one scenario to the other.
Variable spending amortizes your assets over the years you have left and re-plans every year from the balance you actually have, the way lifecycle economics has said to since Samuelson and Merton in 1969. Fixed expenses come first. Everything above them flexes with the market, so across a thousand trials you see a range of retirements instead of a pass or fail.
How FinZot models variable spending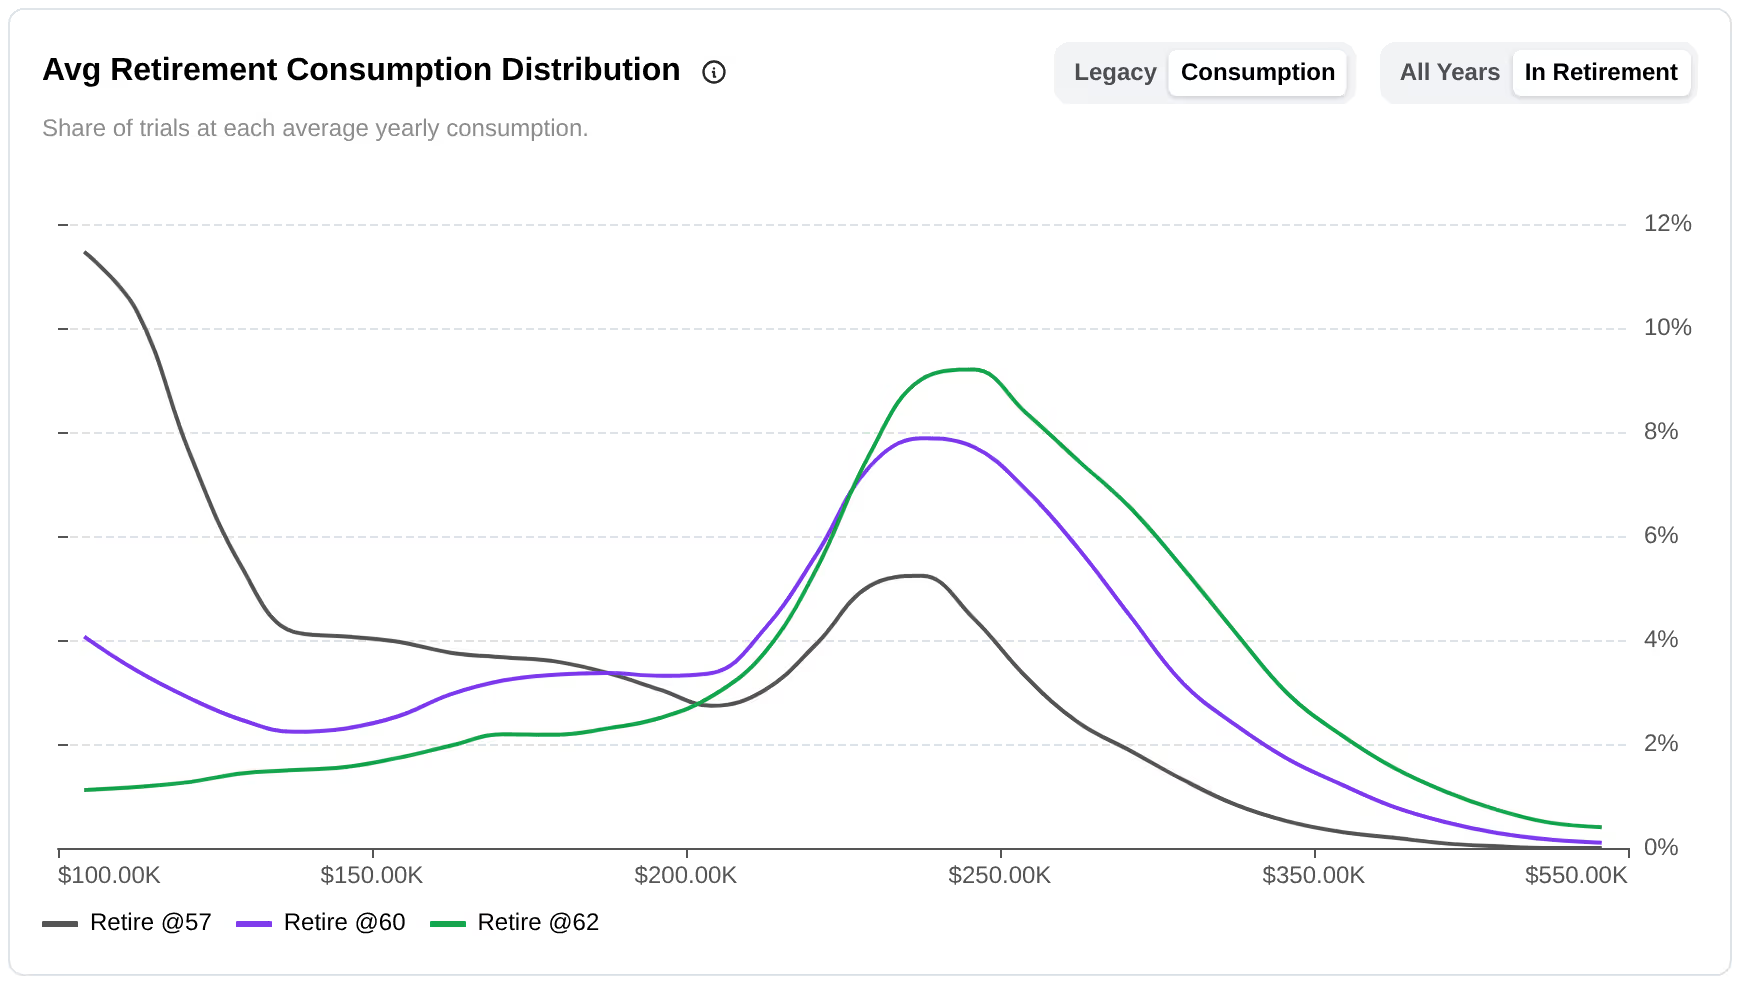
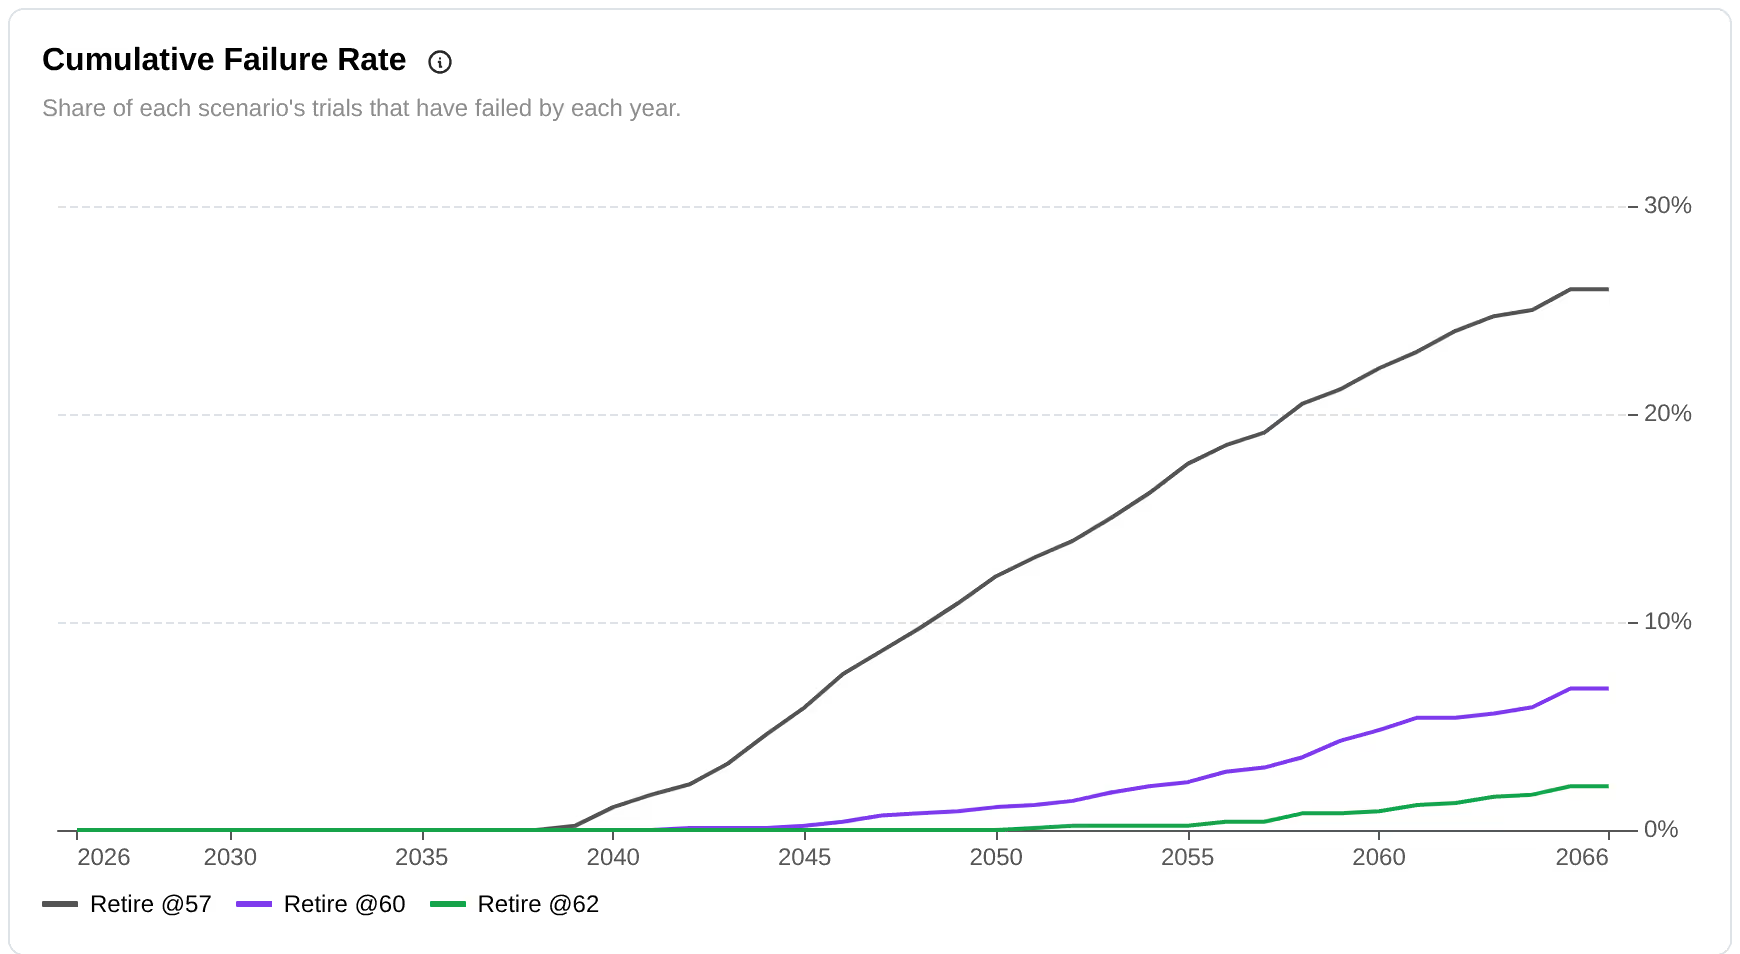
A thousand Monte Carlo trials, each stitched from blocks of consecutive years of real market history rather than drawn from a bell curve, and each a full tax-aware run of your plan. See when and how often a fixed budget breaks.
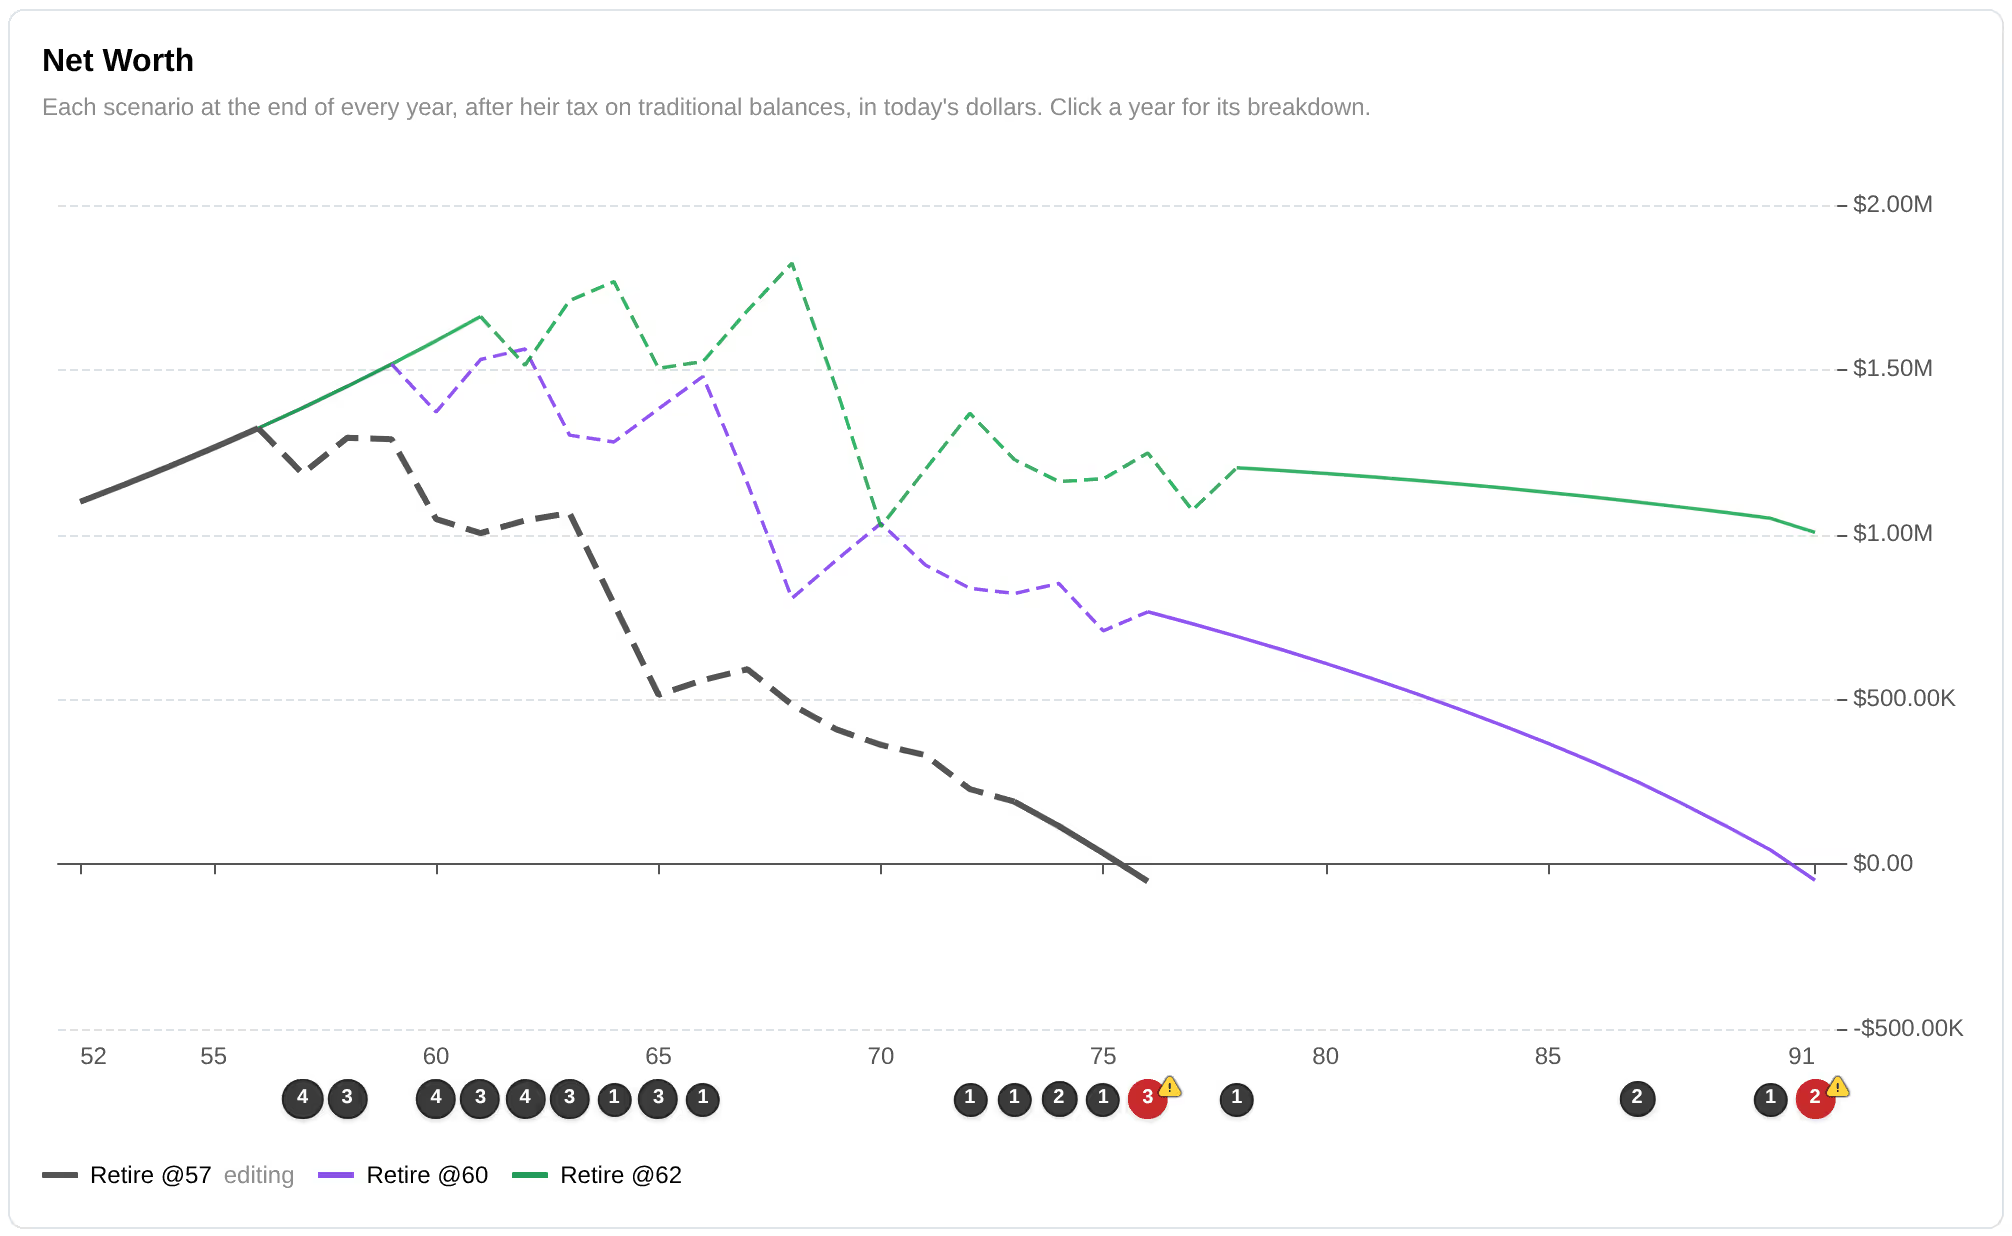
How FinZot's Monte Carlo worksReplay your plan through real market history. Here all three scenarios retire into 1966 and the stagflation that followed. Dashed years are the replay.
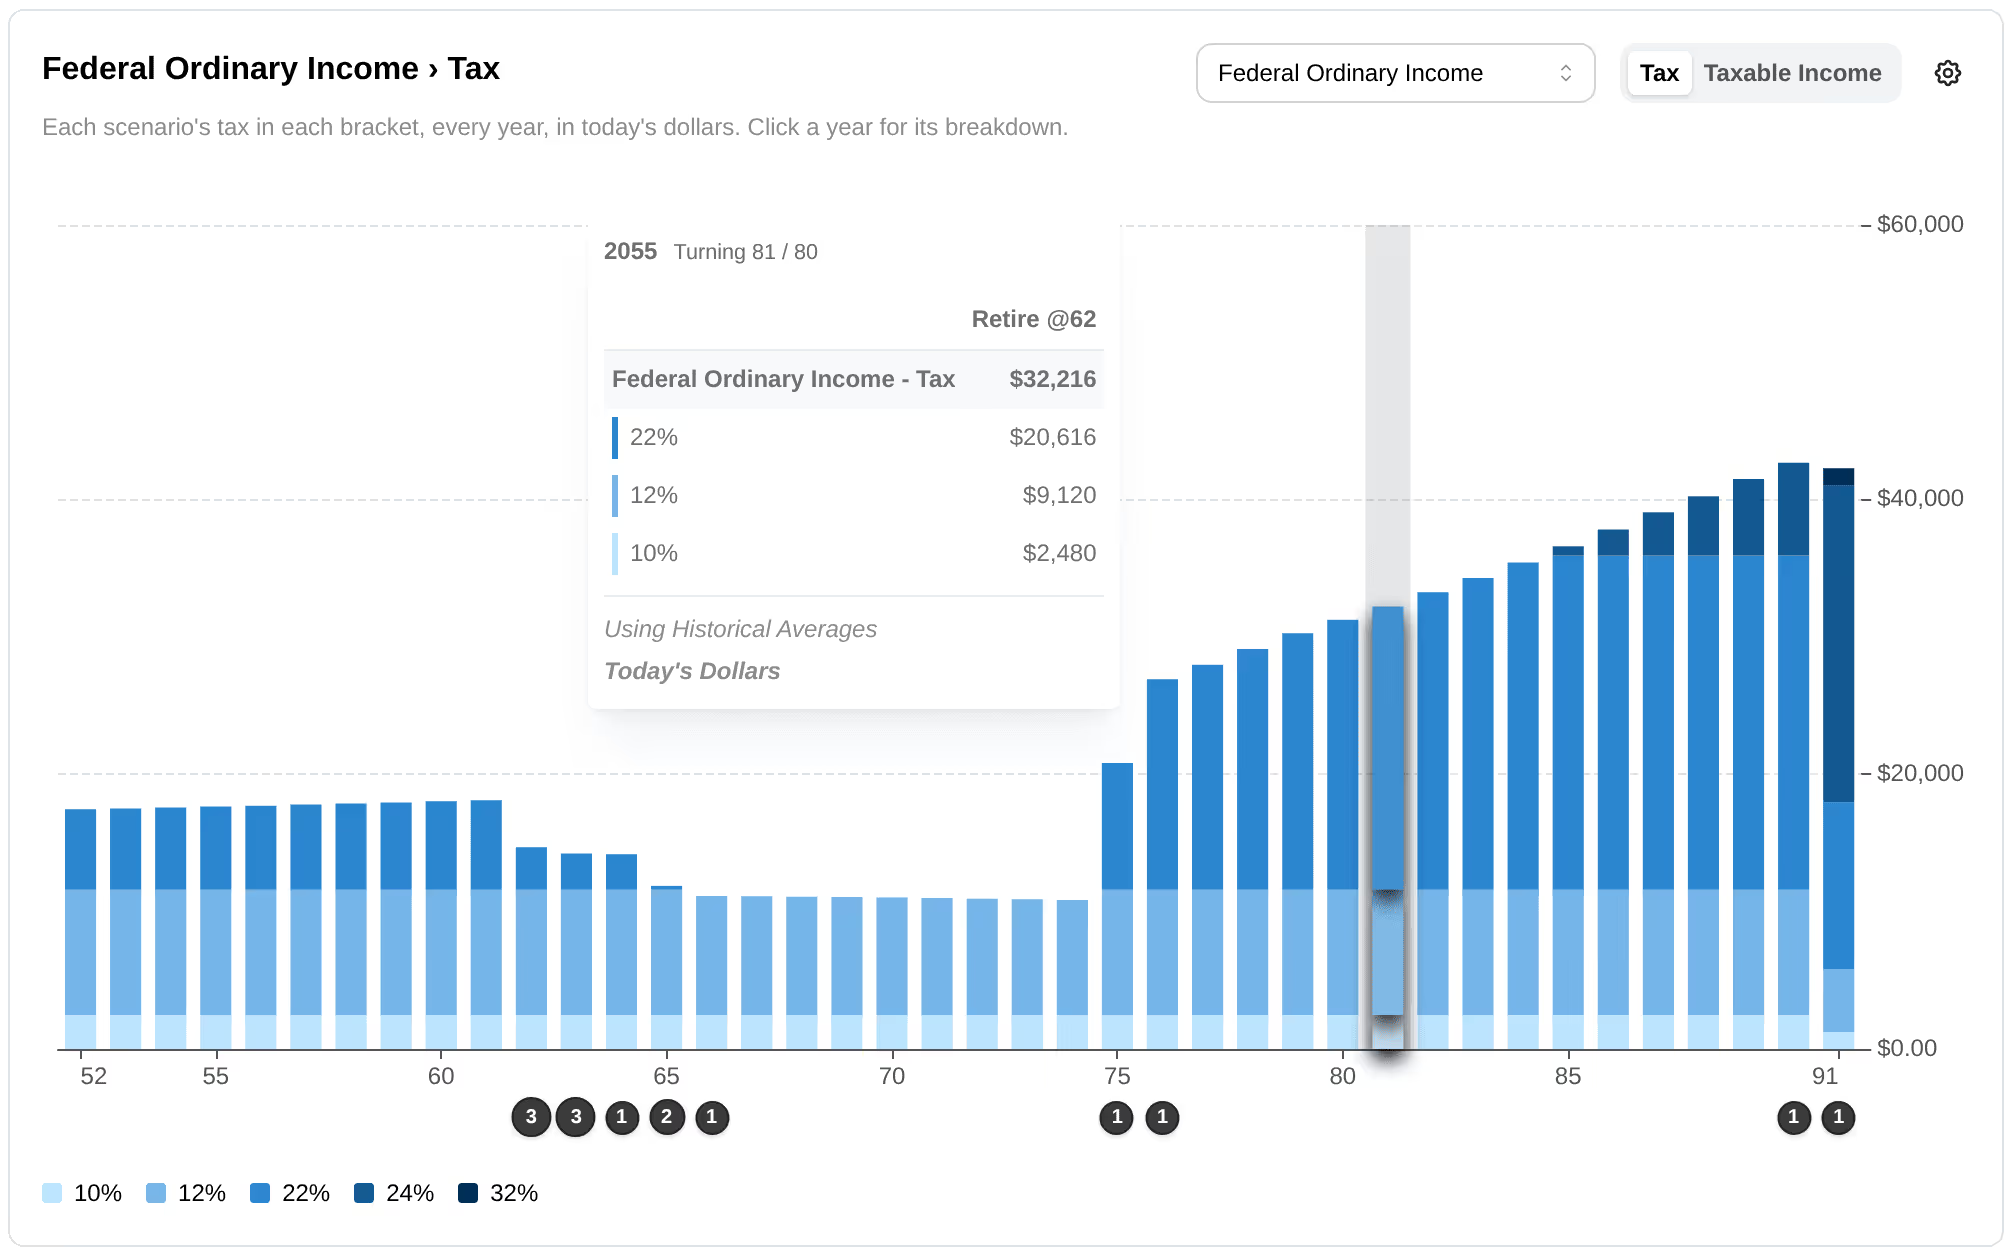
Federal income tax by bracket for the retire-at-62 scenario. Tax falls at retirement, then required minimum distributions at 75 push the plan into the 22% bracket and, from 85, the 24%. The last bar is the surviving spouse filing single.
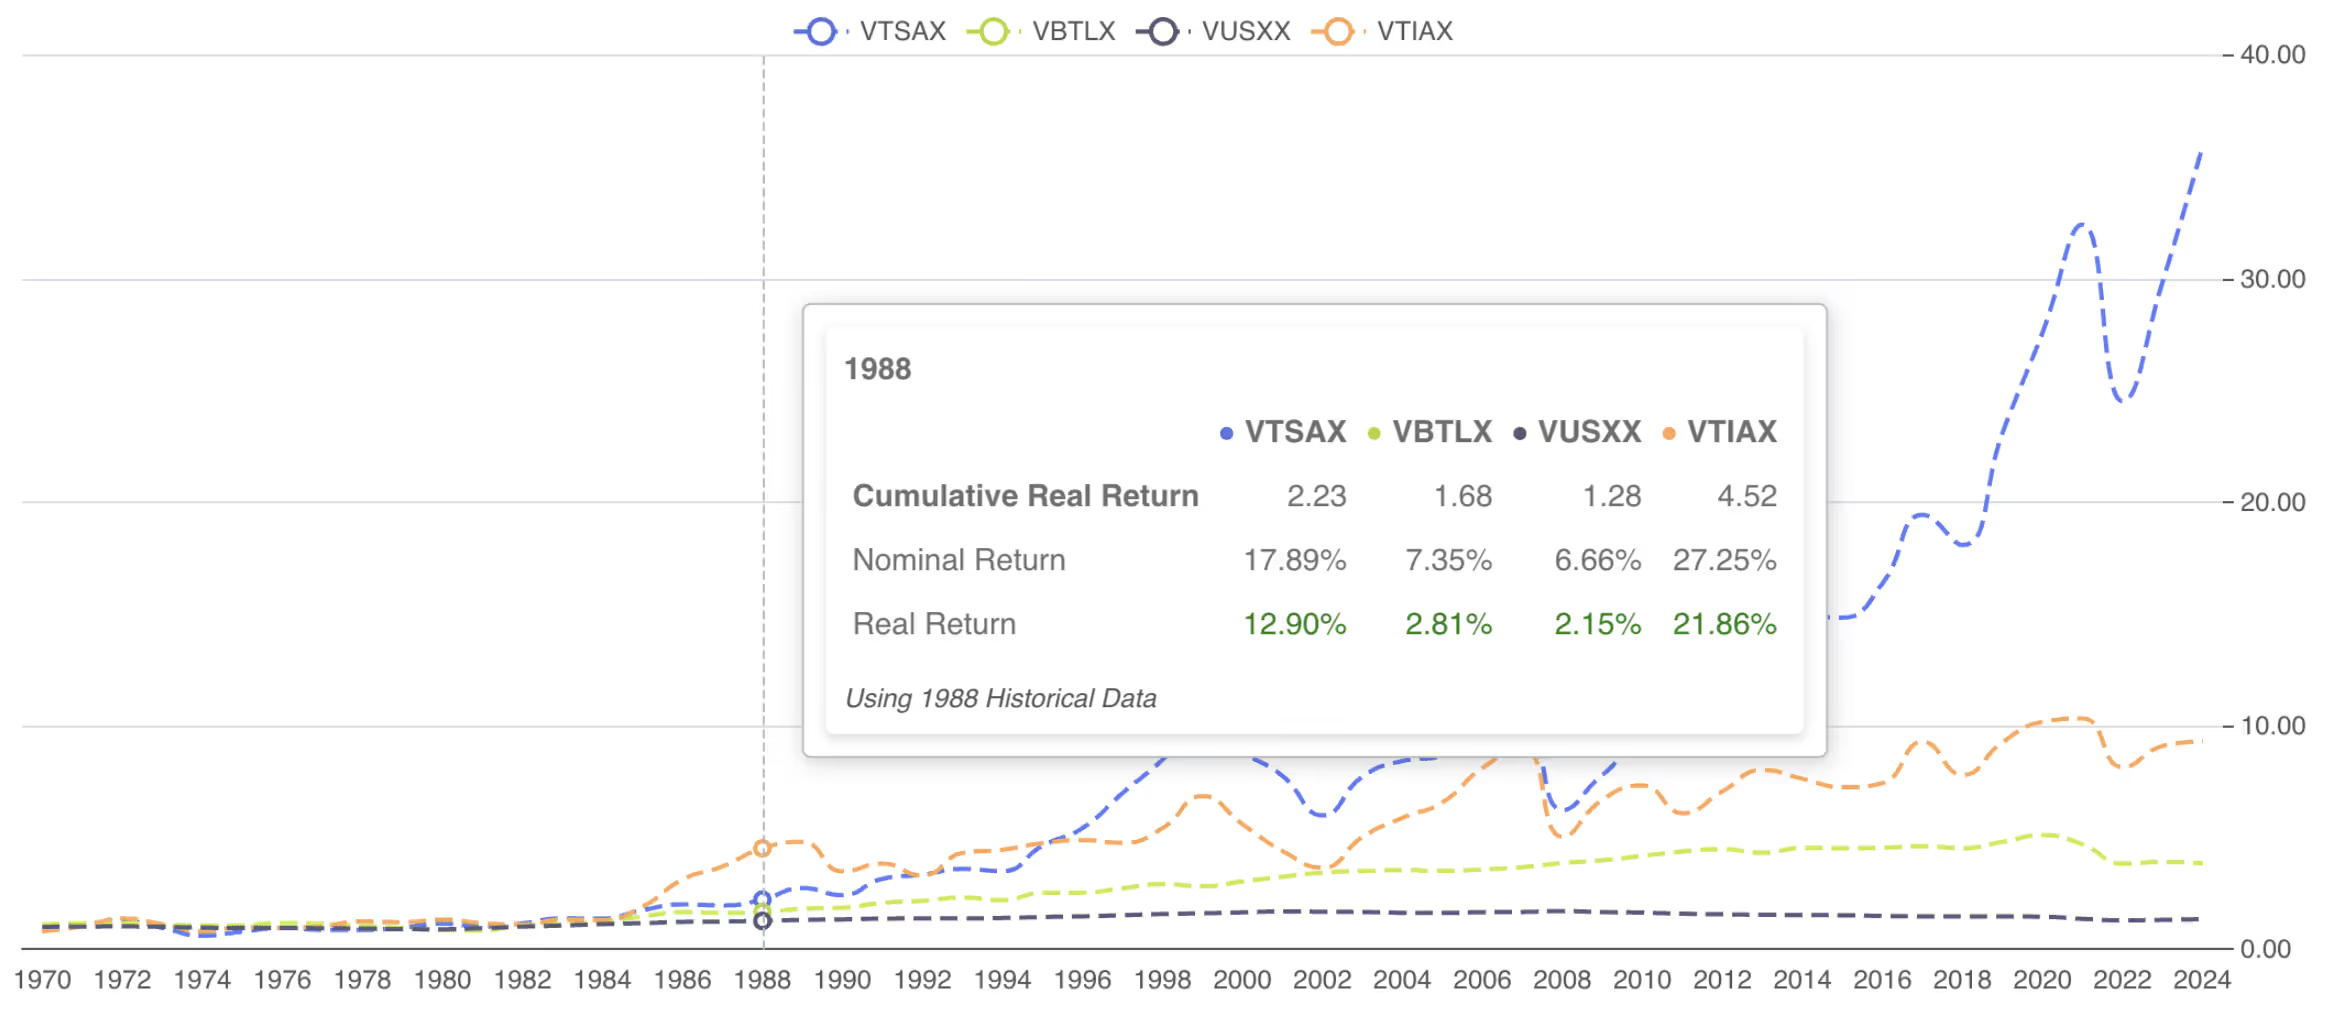
How FinZot models Roth conversionsDefine investment assets using real index funds such as VTSAX, VBTLX, and VTIAX.
What FinZot Covers
Connect Claude, Anthropic's AI assistant, to your FinZot account and work on your plan in plain English.
Model your full family timeline — marriage, children, moves, and life expectancy.
Track every income source — salary, stock compensation, side income, pensions, Social Security.
Optimize 401(k)s, IRAs, HSAs, and 529s with detailed contribution modeling.
Detailed allocations, strategic withdrawals, and exact per-transaction tax impact.
Real index fund history by default, with your own assumptions layered on top.
Model primary homes and rentals — taxes, depreciation, and sales.
Track every liability and model custom payoff strategies.
Capital gains stacked on ordinary income, Social Security's 50% and 85% tiers, AMT, NIIT, IRMAA, ACA credits, and the retirement income rules of 41 states and DC, every year of the plan.
A spreadsheet-like formula engine that makes your plan react to life.
Test resilience against history and compare what-if futures side-by-side.