Serious DIY financial planning software
Go deeper with Claude AI
The plan above started as one message.
A real conversation in claude.ai. Claude asks what it needs, builds the plan, runs the projections, and saves it to your account. Or build it yourself in the app.
Can you help me create a brand new FinZot plan? I'm a 52-year-old teacher in CA making $84k with a pension. My wife makes $86k and is also a teacher with a pension. We plan to retire at 62. … Start the plan and ask me questions where you need more details.
- Start session
- Read reference docs
- List pension plans
- Show pension plan
I'll get this started, but a plan like this depends on a handful of specifics that change the numbers, especially your pension formula and how you'll bridge health insurance before Medicare.
- Are you both CalSTRS Classic (2% at 60, hired before 2013), or does PEPRA (2% at 62) or CalPERS apply to either of you?
- Does either of you have Social Security-covered work history outside CA public teaching?
- Retiring at 62 leaves a three-year gap before Medicare. How will you cover health insurance?
- Birth years, and the CalSTRS service credit each of you has earned so far. A career bonus kicks in at 30+ years.
- Cost basis on the taxable account, and whether a 70/30 stock/bond mix is right for you.
Both CalSTRS Classic. No Social Security for either of us. Not sure about health insurance yet. Born Jan 1974 and Jan 1975, 20 and 21 years of service credit. $320k basis. 70/30 is fine.
- Create plan
- Edit plan
- Run projection
- Publish plan to account
Your plan is built and saved to your FinZot account: Open Two teachers, CalSTRS →
What the numbers show. I put in a placeholder $12k a year each for ACA coverage from retirement until Medicare at 65 that you can adjust later, and assumed 8% a year for stocks, a little below their long-run history. Your pensions carry most of your spending. Once you're both retired, combined pension income is about $124k a year in today's dollars against $139k of expenses including the health bridge. The portfolio makes up the difference until Medicare kicks in, and after that the pensions cover nearly all of it. Net worth grows from $1.26M today to roughly $2.0M the year you're both retired. I ran 1,000 Monte Carlo trials against historical market variance and the plan is solvent in 979 of them.
Add two more scenarios: what if we both retire at 57, or at 60?
- Edit plan
- Run projection
- Query results
- Publish plan to account
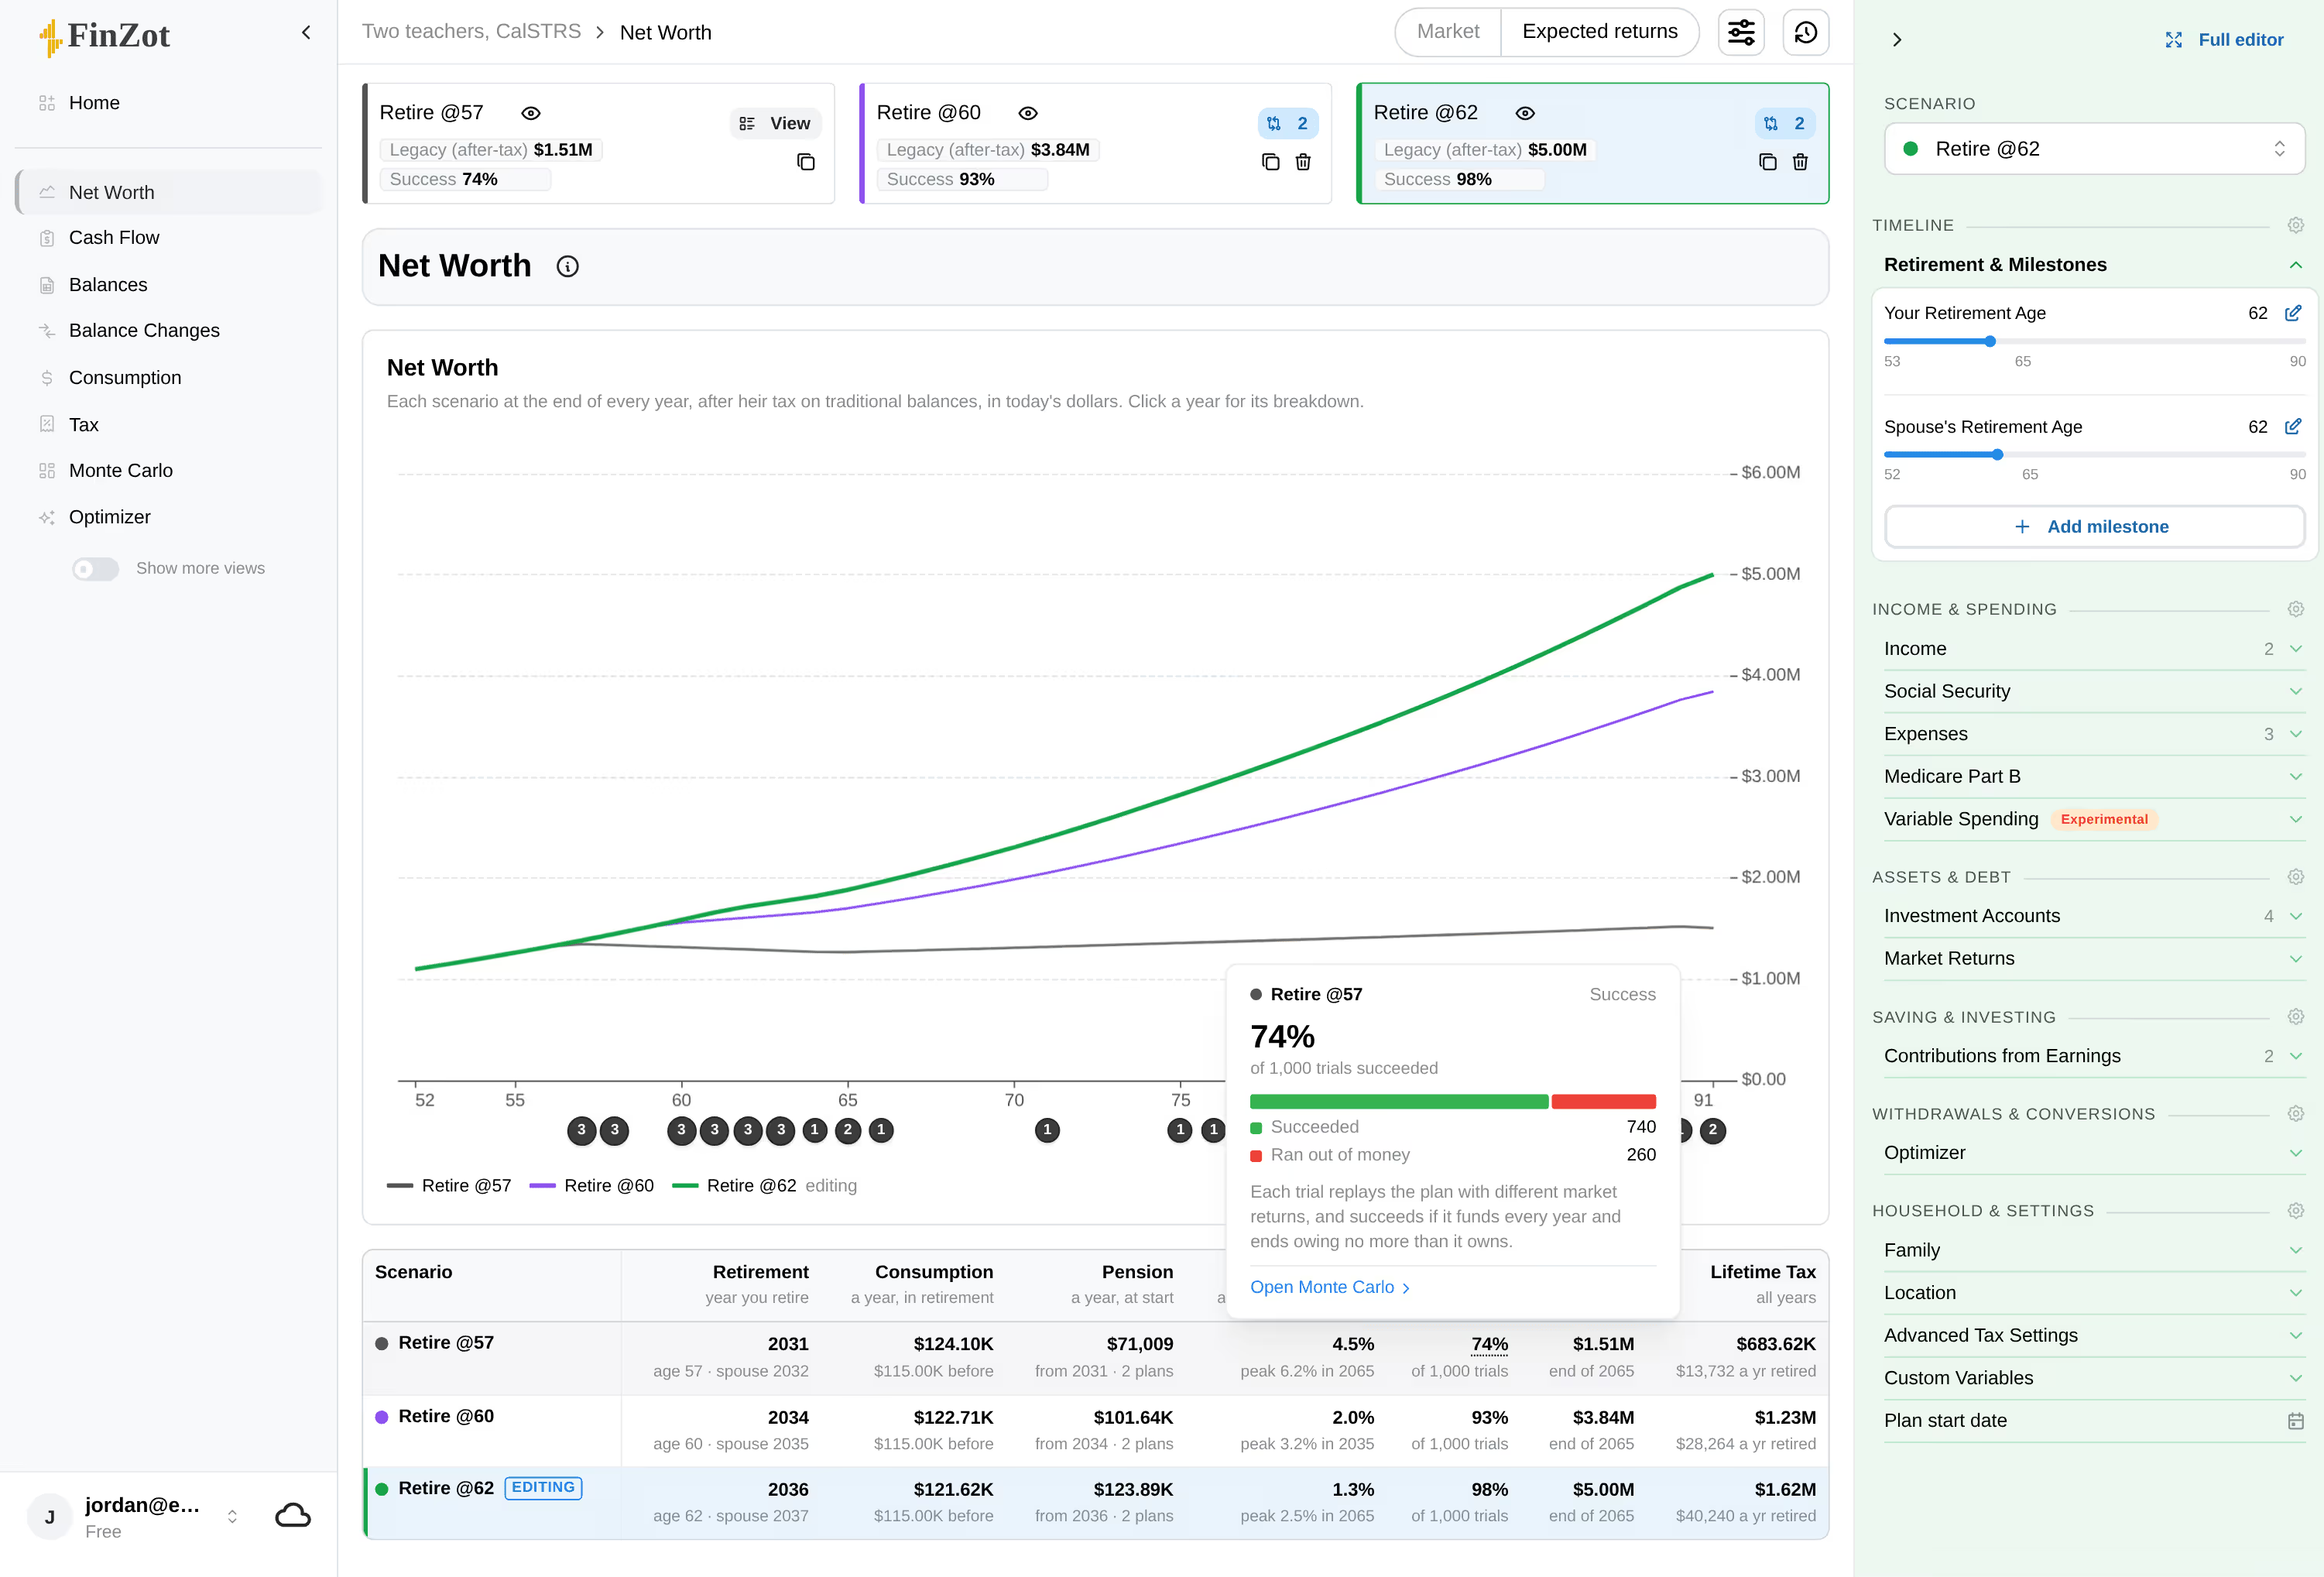
Added both to the same plan. Retiring earlier costs you twice under CalSTRS: fewer years of service credit and a lower age factor (1.64% at 57 against 2.4% at 62), so combined pension income drops to about $71k at 57.
Retire @57
- Success
- 74%
- Legacy
- $1.51M
- Pension
- $71k
Retire @60
- Success
- 93%
- Legacy
- $3.84M
- Pension
- $102k
Retire @62
- Success
- 98%
- Legacy
- $5.00M
- Pension
- $124k
Retiring at 60 holds up in most trials. At 57, the portfolio carries five extra years of the health bridge on a smaller pension, and the plan falls short in about a quarter of them.
Everything in this conversation ran through FinZot's Claude connector, free for a limited time with a FinZot account. See pricing.